Settlement
Value grounded in its verified source, ownership and continuity. Settlement Notes preserve the exact Phi locked into them. Their dollar display is a valuation of that native amount.
Keep the value connected to its evidence.
Reality-Grade Banking
Hold the original. Verify what is yours.
Keep its history connected as it moves.
The premise
A number tells you how much. Proof lets you examine where that value comes from, who owns it and what happened to it.
Reality-Grade Banking connects those facts to the original source. Your account brings value, ownership and history together. The evidence travels with the value, so another conforming system can check it against the same rules.
The source establishes the facts.
Verification establishes what passes.
What that gives you
Your saved proof is more than a link to somebody else’s page. It carries the evidence that a compatible verifier can inspect, even when that page is unavailable.
A completed transfer connects the next owner to the same value and its prior history. An image, a message or a payment request alone does not move ownership.
Check the original source, the ownership it establishes and the history it carries. Verification follows defined rules. A label or a successful-looking screen cannot replace it.
Continuity
Change the interface. Keep the evidence.
You should be able to explain what you own without asking someone to trust a screenshot. An original proof makes its supported claims inspectable. A shared account proof can show the disclosed identity, balances and history without sharing a signing key or account access.
Continuity means the receiving system preserves those connections. It does not start a new story that forgets where the value came from. A conforming receiver must demonstrate that it can verify and preserve the evidence it handles.
Beyond a connection
A funded note puts an original proof in an image you can keep. Enter one amount; your account supplies its funding automatically. The original carries every funding component and its source.
Connected creation works through your account. Conforming prepared custody also supports creation and continuous transfers offline. Deposit verifies the complete source and consumes the received note once before accepting its credit. The original proof stays authoritative as the record moves. A copied picture cannot create new money.
How notes work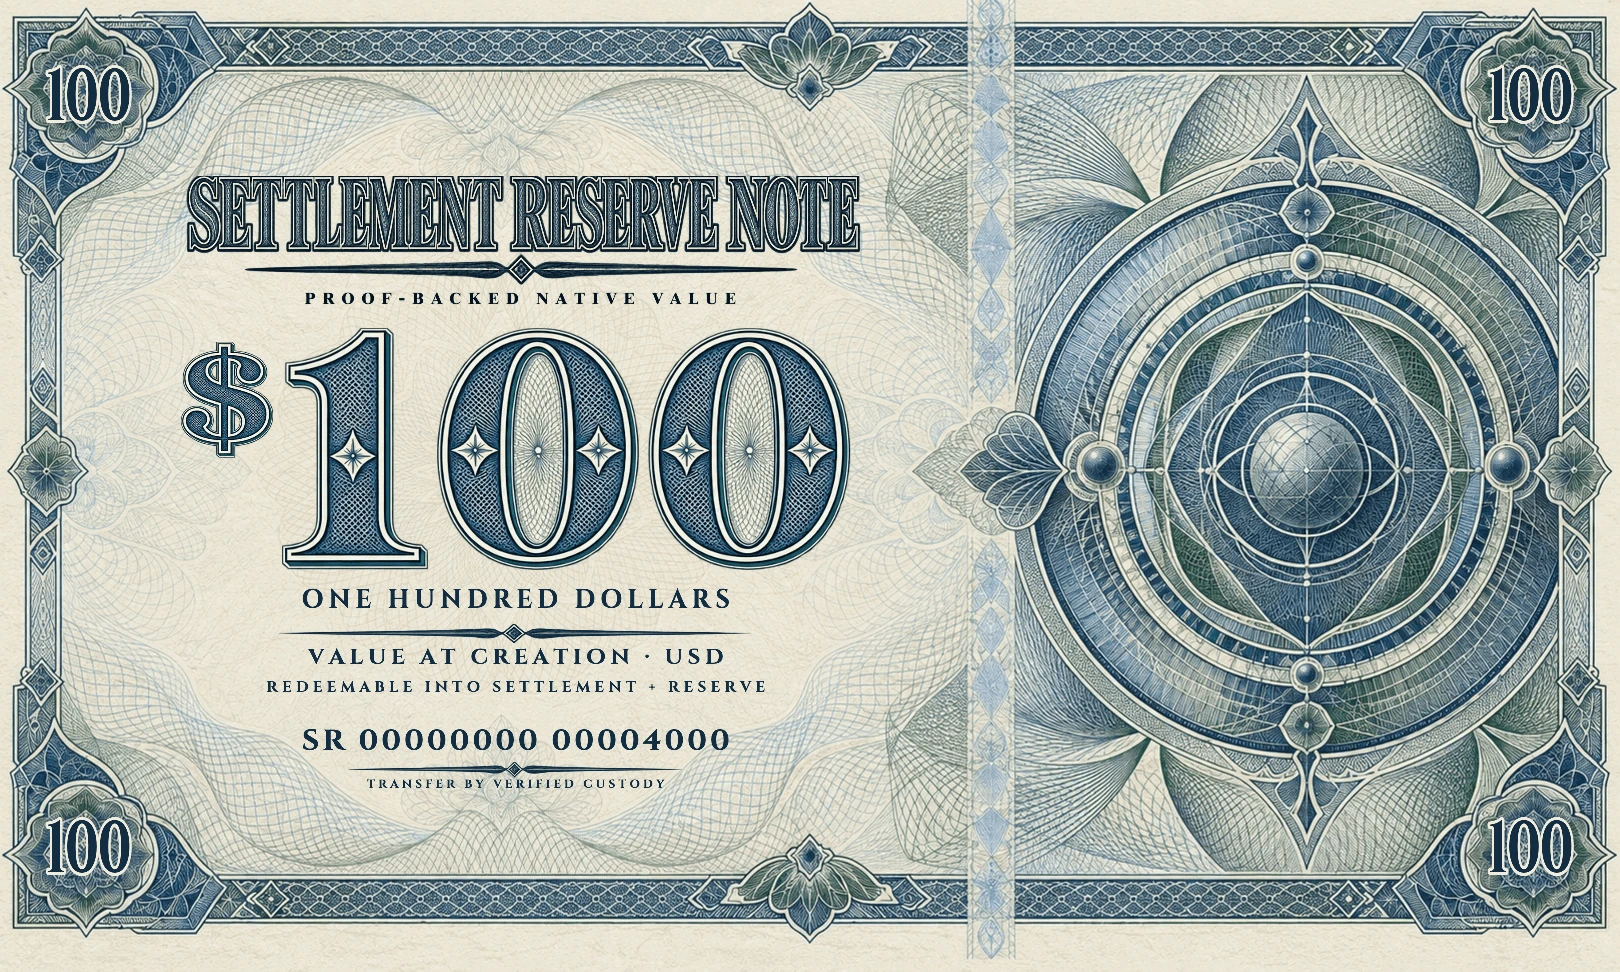
Two forms of value
Value grounded in its verified source, ownership and continuity. Settlement Notes preserve the exact Phi locked into them. Their dollar display is a valuation of that native amount.
Keep the value connected to its evidence.
Funded value with an inspectable backing source. Reserve Notes preserve their original dollar denomination.
Use funded value with a clear source.
Choosing an available legacy payment route moves funds outside proof continuity. Your transfer receipt remains verifiable; the receiving balance does not carry the same source, ownership and history.
Understand Settlement and Reserve See how value is calculatedThe receiving standard
Value does not lose its proof because the next institution has a different interface. A receiving system must demonstrate that it can handle the source correctly.
Inspect conformanceInspect the original evidence and its exact bindings. Reject altered or incomplete sources.
Respect the current owner, exact authorization and protected custody. Prevent duplicate spending.
Connect each accepted change to its predecessor. Keep results verifiable and recoverable.
What the standard means
A receipt image shows a claim. An original proof carries verifiable source material. A compatible verifier checks integrity and the actual claims and ownership bindings carried by that source. Recompressing or screenshotting a proof image can remove that material.
Verification applies the protocol’s rules to the admitted source and its trust and custody bindings. Infrastructure makes those rules and transports available. A server response, brand name or account signature alone cannot supply funding or override the source.
Keep the complete original, the matching verifier and the device-held resources needed for the operation. Offline note spending requires previously funded qualified custody and prepared receiving and issuance resources. A saved balance can be an observation; it is not by itself a funding proof or evidence that no later transaction exists.
A result applies to the exact implementation, capability and evidence assessed. Passing a reference verification run does not certify every financial operation or institution. A verified failure is nonconforming for the assessed proof-continuity requirements until corrected and reassessed. Missing evidence means conformance has not been demonstrated.
A public account proof is a separate disclosure of supported account facts. Its source can be inspected without your signing key or Identity Record. You choose whether to publish a snapshot and whether to enable future public updates. Turning off live sharing stops future disclosure through that link; already published copies can remain available.
Open implementation
The rules should be open to the people expected to rely on them. The public repository brings together the reference application, matching native source, verification tools and institutional integration guidance.
Developers can study, modify and redistribute the covered code under GNU GPL v3. Institutions can implement the receiving requirements and demonstrate their results. Branding and conformance claims have their own published terms.
Bankeiz.com is the official reference implementation. Receiz supplies the underlying proof infrastructure and v129 SDK, MCP and AI skills.